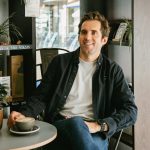


Many early-stage boards are assembled around names, networks, and goodwill — and fail to challenge the founders who need it most. A governance practitioner with a track record in startup boards breaks down what genuine oversight looks like below €5M in revenue, why mandatory co-investment undermines independence, and how to spot the difference between a real board and theatre. Interview with Bruno Monfils, ILA Startup & Scaleup Committee Member.
You argue that requiring board members to invest undermines their independence. But many founders argue that “skin in the game” improves commitment and judgment. How do you reconcile those two views?
For early-stage boards, alignment is possible without cash investment. A director needs to be aligned with success, but independence requires freedom from material financial relationships. A significant personal investment can become the dominant, distorting factor in a director’s thinking. In sub-€5M revenue companies, the board’s role is closer to advisory than institutional oversight. So the most valuable contribution is the director’s time, availability, and judgment. Equity-based compensation, vesting over time, creates economic alignment without turning the director into a mini-investor. When a director writes a large cheque, they may push for risky strategies to protect their position or disengage after investing. An independent director, paid through equity or fees, knows their value is measured in what they bring to the table. “Skin in the game” should be time, attention, and a clearly structured equity package, not a mandatory capital ticket. This protects independence while providing real upside.
“If a board never asks “who owns this decision?” or “how will we know if this was wrong?”, it is doing theatre.”
Bruno Monfils, ILA Startup & Scaleup Committee Member
For startups below €5M in revenue, what does meaningful board contribution look like in practice — and how do you distinguish genuine oversight from theatre?
Below €5M in revenue, the board’s job bis mostly building governance foundations: decision discipline, role clarity, and risk awareness. Meaningful boards do three things: First, they help the founder team turn chaos into traceable decisions. That means clear agendas, structured pre-reads, and formal minutes recording the “why” and the “who”. If a board never asks “who owns this decision?” or “how will we know if this was wrong?”, it is doing theatre. Second, they use their network. Introductions are vital, but only if directors follow up, open doors, and stay engaged on outcomes.
Real follow-through is the contribution. Third, they target core risks: runway, key-person dependency, and regulatory exposure. They don’t run the company, but they demand management explains its assumptions. Oversight is theatre when meetings rely on storytelling with no challenge or tracking.
How do you identify, in a board interview, whether a candidate can provide the constructive challenge a founder needs, versus someone who will default to validation?
The most useful test is how the candidate differentiates between founders and CEOs. An effective board member distinguishes between the founder’s creative spark and the CEO’s responsibility to build a scalable organization. They should cite examples where they helped a founder transition from “heroic mover of mountains” to “builder of systems and teams.” You can probe this directly. Ask them to describe a time they strongly disagreed with a founder. The answer should include palpable tension i.e.the healthy friction that exists when challenging a founder on the necessity of long-term planning. The tension resolves when the founder switches to CEO mode. This is the board member’s core value: using the boardroom as a safe space to challenge the founder into CEO mode, ensuring they are not just validating the status quo but actively improving the business’s maturity.
“[…] directors are expected to prepare, bring industry expertise, and feel obliged to ask the difficult, unpopular questions.”
Bruno Monfils, ILA Startup & Scaleup Committee Member
You contrast ILA-style governance with boards built around wealthy friends or investors. What is the most dangerous governance pattern you have seen that started with good intentions?
The most dangerous pattern is the “vanity board”: a group assembled around big names, impressive CVs, or friendly investors, rather than the competencies the company actually needs. The intent is often positive (market credibility or signaling) but the result is a board structurally unable to challenge the business. Vanity boards meet infrequently, rely on management’s narrative, and avoid uncomfortable topics. Because directors are chosen for who they are rather than what they contribute, there is little expectation of preparation, industry homework, or engagement between meetings. Important decisions are made outside the room, and formal meetings are just going through the motion. This is the opposite of skills-based governance: a culture where directors are expected to prepare, bring industry expertise, and feel obliged to ask the difficult, unpopular questions.
At what revenue or headcount threshold does the nature of what a board needs to provide fundamentally change — and what signals tell you that threshold has been crossed?
In my experience, a practical threshold is often €3 to €5M in revenue or 30 to 50 employees. Below that, the board’s focus is product-market fit and existential risk. Above it, the role shifts to monitoring execution, oversight, and scalability. You see this transition in business signals: entry into new countries, larger contracts, or complex regulatory requirements. Another sign is the appearance of a C-suite layer, meaning the founder is no longer close to every decision. The board must then ask about succession and organizational health. The discussion changes from “how do we survive?” to “what is the path to €50M and what are the risks?”. The board moves from a service-only role to a mix of service and monitoring. It must ensure financial reporting is effective, internal controls exist, and there is a clear documentation trail for key decisions. Scaling requires moving away from informal, founder-led processes toward institutional ones.
Editor’s note: As part of the collaboration between Silicon Luxembourg and ILA, members of the ILA Startup and Scaleup Committee are sharing their stories on governance. These reflect their personal views only and do not necessarily represent the official position of ILA.